 how-to
How Can You Secure Low Auto Interest Rates?
Last Updated: November 1, 2026
Quick Summary
You can secure low auto interest by improving your credit score before applying, making a larger down payment, and choosing a shorter loan term. Get pre-approved with several lenders inside one short shopping window, then use those written offers to negotiate a better rate at the dealership. Always compare APR and total repayment, not just the monthly payment.
- Your credit score and history are the single biggest factor in the auto interest rate you are offered.
- Stretching a loan to 84 months lowers your monthly payment but raises your total interest.
- Pull credit reports 8 to 12 weeks out, dispute errors in writing, and pay down revolving balances.
- Prequalification uses a soft inquiry; pre-approval is a firmer offer that may involve a hard inquiry.
- Ask each lender for the APR and total repayment in writing, and treat missing figures as a warning sign.
Table of Contents
- What Determines Your Auto Interest Rate
- How to Improve Your Credit Score Before Applying for a Car Loan
- Why Car Loan Pre-Approval Gives You Use
- APR vs Interest Rate: What You Actually Pay
- Car Loan Interest Rate Negotiation at the Dealership
- When Car Loan Refinancing Makes Sense
- Compare Your Financing Options at Automaxx
- Frequently Asked Questions
What Determines Your Auto Interest Rate
Auto interest is the cost a lender charges you to borrow money for a vehicle, quoted as an annual percentage rate on the balance you owe. Two buyers can finance the same car and pay very different amounts. The difference comes down to a handful of factors you can actually influence.
Lenders price risk. The riskier you look on paper, the higher the rate they charge to protect themselves.
Here is what moves your auto interest rate up or down:
- Credit score and history - the single biggest factor
- Loan term length - longer terms usually cost more
- Down payment size - more cash down means less risk for the lender
- Vehicle age and type - older cars often carry higher rates
- Debt-to-income ratio - how much of your income is already committed
Credit Score and Credit History
Your credit score is a number lenders use to predict how reliably you repay debt. Credit scores are typically reported on a numeric scale, and a higher score generally means a better rate you may qualify for (Credit report and score basics).
Your credit history matters just as much as the score itself. Lenders look at how long you have held credit, whether you pay on time, and how much of your available credit you use.
If you have no credit history at all, there are still paths forward. Our guide on 7 ways to get a car loan in Alberta with no credit walks through the options that actually work for a thin credit file.
Loan Term, Down Payment, and Vehicle Age
Three levers sit entirely in your hands, and most buyers ignore two of them.
Loan term is how long you take to repay. Stretching a loan to 84 months lowers your monthly payment but raises your total interest.
Down payment reduces the amount you borrow.
Vehicle age affects risk. Lenders know older vehicles are worth less if they need to repossess, so they charge more.
Weighing a used car against a new one changes these numbers fast. Our used vs new car cost guide compares total cost of ownership, depreciation, financing, and fees.
How to Improve Your Credit Score Before Applying for a Car Loan
Improving your credit score before you apply is the highest-return move available to most buyers. A better score can lower your auto interest rate for the entire life of the loan, not just the first month.
Start well before you plan to apply. Here is the order we recommend:
- Pull your credit reports from both national bureaus and check for errors. Dispute anything wrong in writing.
- Pay down revolving balances. Credit cards hurt your score most when they sit near their limits.
- Stop opening new credit. Each application adds a hard inquiry and can ding your score.
- Set up automatic payments so you never miss a due date.
- Keep old accounts open. Length of credit history helps your score.
A common mistake is applying for a car loan the same week you decide to buy. Give your score time to reflect the work you have done.
If your credit is weak, a bad-credit car loan may still be within reach.
Why Car Loan Pre-Approval Gives You Use
Car loan pre-approval is a lender's written offer to finance you up to a set amount at a set rate before you pick a vehicle. It turns you from a shopper hoping for approval into a buyer with a number in hand.
First-time buyers often benefit most from pre-approval. Our auto financing for first-time buyers guide explains how to get approved and build leverage before you shop.
A Step-by-Step Application Timeline
Most buyers start too late. Work backward from the day you want to drive off the lot:
- 8 to 12 weeks out: Pull your credit reports from both national bureaus, dispute errors in writing, and pay down revolving balances. Do not open new credit.
- 4 to 6 weeks out: Gather proof of income (recent pay stubs), proof of residence, and banking information. Decide on a realistic down payment and total budget, including insurance and registration.
- 2 to 4 weeks out: Get prequalified with several lenders inside a single shopping window (see below). Prequalification is a soft inquiry and does not affect your score.
- 1 to 2 weeks out: Convert your best prequalification into a formal pre-approval. Ask for the approval amount, rate, APR, term, and expiry date in writing.
- At the dealership: Negotiate the vehicle price first, then present your pre-approval and ask the finance office to beat it. Do not let the finance office combine the trade-in, financing, and add-ons into one conversation.
Rate Shopping and Hard Inquiry Rules
Rate shopping is the practice of gathering quotes from several lenders within a short window. It works because credit bureaus treat a cluster of auto loan inquiries as a single shopping event rather than a string of desperate applications.
Multiple auto loan inquiries made within a short period are generally grouped together by credit bureaus, so it helps to do your shopping within a focused window.
- Get quotes from banks, credit unions, and online lenders
- Keep every inquiry inside the shopping window
- Compare the full offer, not just the rate
- Ask each lender for the APR in writing
Buyers who compare several lenders often see different offers on the same vehicle, so the first quote is not always the best one.
How to Use a Pre-Approval at the Dealership
Bring your pre-approval letter and a one-page comparison of your other quotes. When the finance manager presents dealer financing, ask three questions:
- What is the APR, not just the rate?
- What is the total interest over the full term?
- What fees are included, and which are optional?
If the dealer's offer beats your pre-approval on APR and total cost, take it. If it does not, use your pre-approval. Either way, you have a benchmark the dealer cannot ignore.
APR vs Interest Rate: What You Actually Pay
The interest rate is the cost of borrowing the principal. The APR is that rate plus fees, expressed as one yearly number.
This is where most buyers get caught. A loan with a low advertised rate can carry a higher APR once origination fees, admin charges, and mandatory add-ons are folded in. A longer term can lower the monthly payment while raising total interest.
A Worked Example
Consider how a lower rate can still cost more. Compare any two offers on the same vehicle by looking at total interest and total repayment, not the monthly payment alone. A longer term can lower the payment while raising the total you pay, and a fee financed into the loan raises the APR above the stated rate.
The Loan Offer Comparison Worksheet
Use one row per lender and one column per figure so every offer is judged on the same basis:
| Field | Lender A | Lender B | Lender C |
|---|---|---|---|
| Interest rate | |||
| APR | |||
| Term (months) | |||
| Fees (origination, admin) | |||
| Monthly payment | |||
| Total interest | |||
| Total repayment | |||
| Early-payoff penalty? |
Ask each lender for every figure in writing. If a lender will not provide the APR or the total repayment, treat that as a warning sign rather than a minor omission.
How Fees and Add-Ons Change the APR
Fees raise the APR because you pay interest on them for the life of the loan. Common examples include origination fees, administration fees, and mandatory products bundled into the financing.
Separate the vehicle price, the financing, the trade-in value, and the optional products into four distinct conversations. When they are bundled, a discount in one area can hide a cost in another.
A loan offer comparison worksheet makes this easy. List each lender in a column. Put the APR, total interest, total loan cost, and monthly payment in rows.
Car Loan Interest Rate Negotiation at the Dealership
Car loan interest rate negotiation is the process of pushing back on the financing terms a dealer presents.
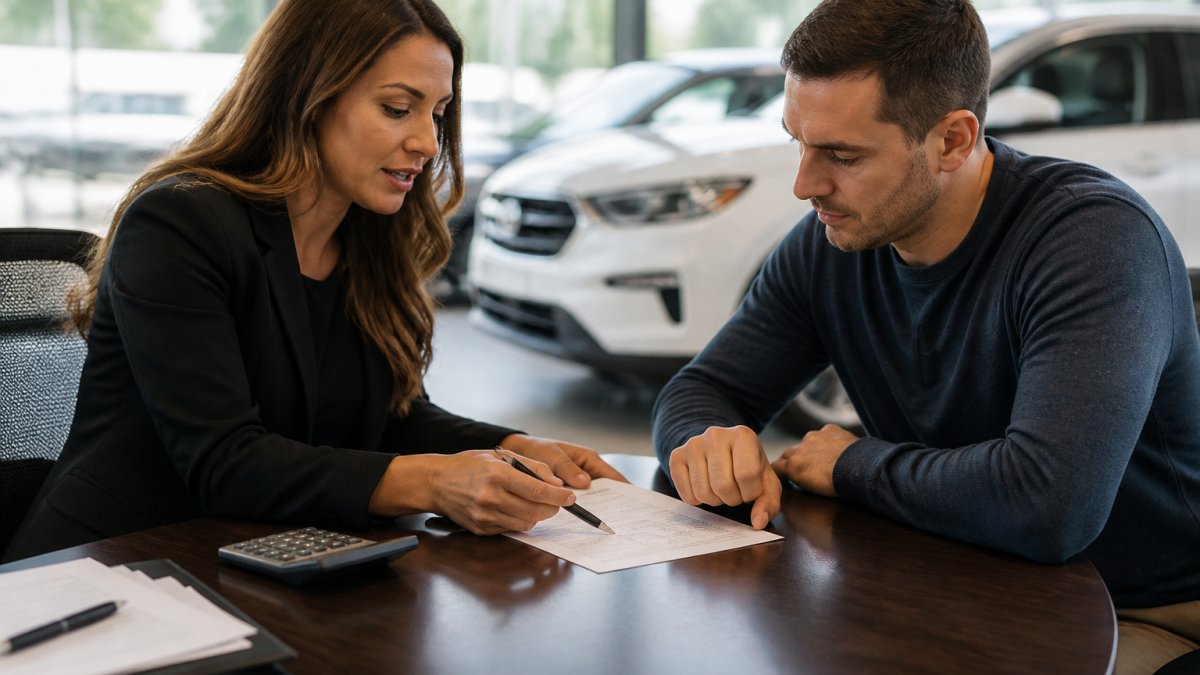
Come prepared with your pre-approved offer. Say plainly: "I have financing at this rate. Can you beat it?" That single question changes the conversation.
Watch out: the finance office is where add-ons get added.
Negotiate the vehicle price first, then the financing.
When Car Loan Refinancing Makes Sense
Car loan refinancing replaces your current loan with a new one, ideally at a lower auto interest rate. Applying these same principles of financial management to other forms of debt can help you secure lower interest rates across your entire portfolio.
The math is simple. Compare the interest remaining on your current loan against the total cost of the new one, including any fees. If the savings beat the cost, refinance.
Refinancing also lets you shorten your repayment term or drop a cosigner once your own credit stands on its own. Check your current payoff amount first, and confirm the new lender charges no early-payoff penalty.
Compare Your Financing Options at Automaxx
Comparing your financing options side by side is the last step before you sign, and it is the one that saves the most money.
Our showroom holds over 250 fully certified, CarFax-verified vehicles, so you can match the right car to the right loan.
Ready to see what you qualify for? Review our financing options and start your application before you visit.
Frequently Asked Questions
What credit score do I need to get a low car loan interest rate?
A higher credit score generally earns a lower auto interest rate. Higher scores generally open up more lender options and offers to compare. A thin or damaged credit file does not lock you out: lenders that work with all credit types weigh income, down payment, and vehicle choice alongside your score. Ask which factors carry the most weight before you apply.
Can I negotiate the interest rate on a car loan?
Yes. The rate a dealer quotes is not always final. Dealers can source financing from several lenders, and a pre-approval from your own bank gives you a benchmark to compare against. Ask what rate the lender approved you for, request a breakdown of fees, and decline add-ons bundled into the financing. A larger down payment or shorter term can also move the number. Get every offer in writing before you sign.
Will applying to several lenders hurt my credit score?
Multiple auto loan inquiries within a short window are typically treated as a single rate-shopping inquiry by credit bureaus, so comparing offers in a focused period has less impact than scattered applications over months. Keep the shopping window tight, use prequalification where available since it usually involves a soft inquiry, and avoid applying for unrelated credit during the same period.
How much can I save by making extra car loan payments?
Extra payments go straight to your principal balance, which reduces the interest charged over the life of the loan. Even a modest additional amount each month can shorten your repayment term and cut total interest. Before you commit, confirm with your lender that there is no prepayment penalty and that extra funds are applied to principal, not to future scheduled payments.
Securing a low auto interest rate comes down to preparation: a stronger credit profile, a real down payment, pre-approval in hand, and the willingness to negotiate. Automaxx makes that process simpler with access to more lenders and programs for better rates, financing for all credit types, and a no-pressure showroom built around transparent pricing. Get started with Automaxx and drive away with financing that fits your budget.